Nitrogen+Syngas 390 Jul-Aug 2024

31 July 2024
Market Outlook
Market Outlook

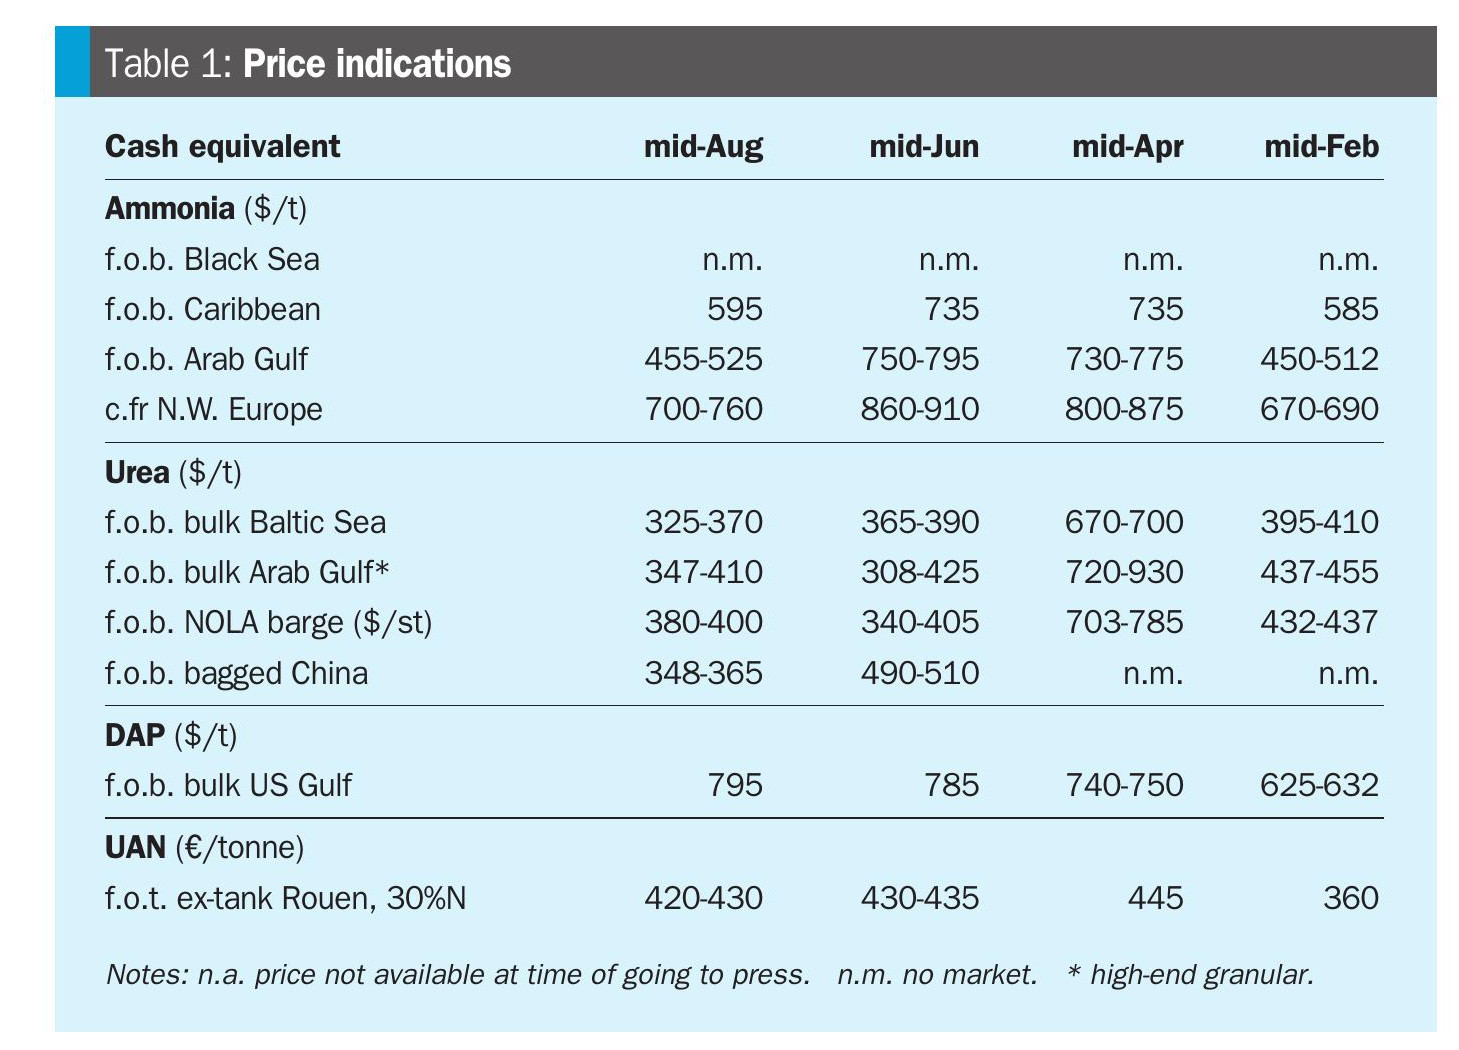
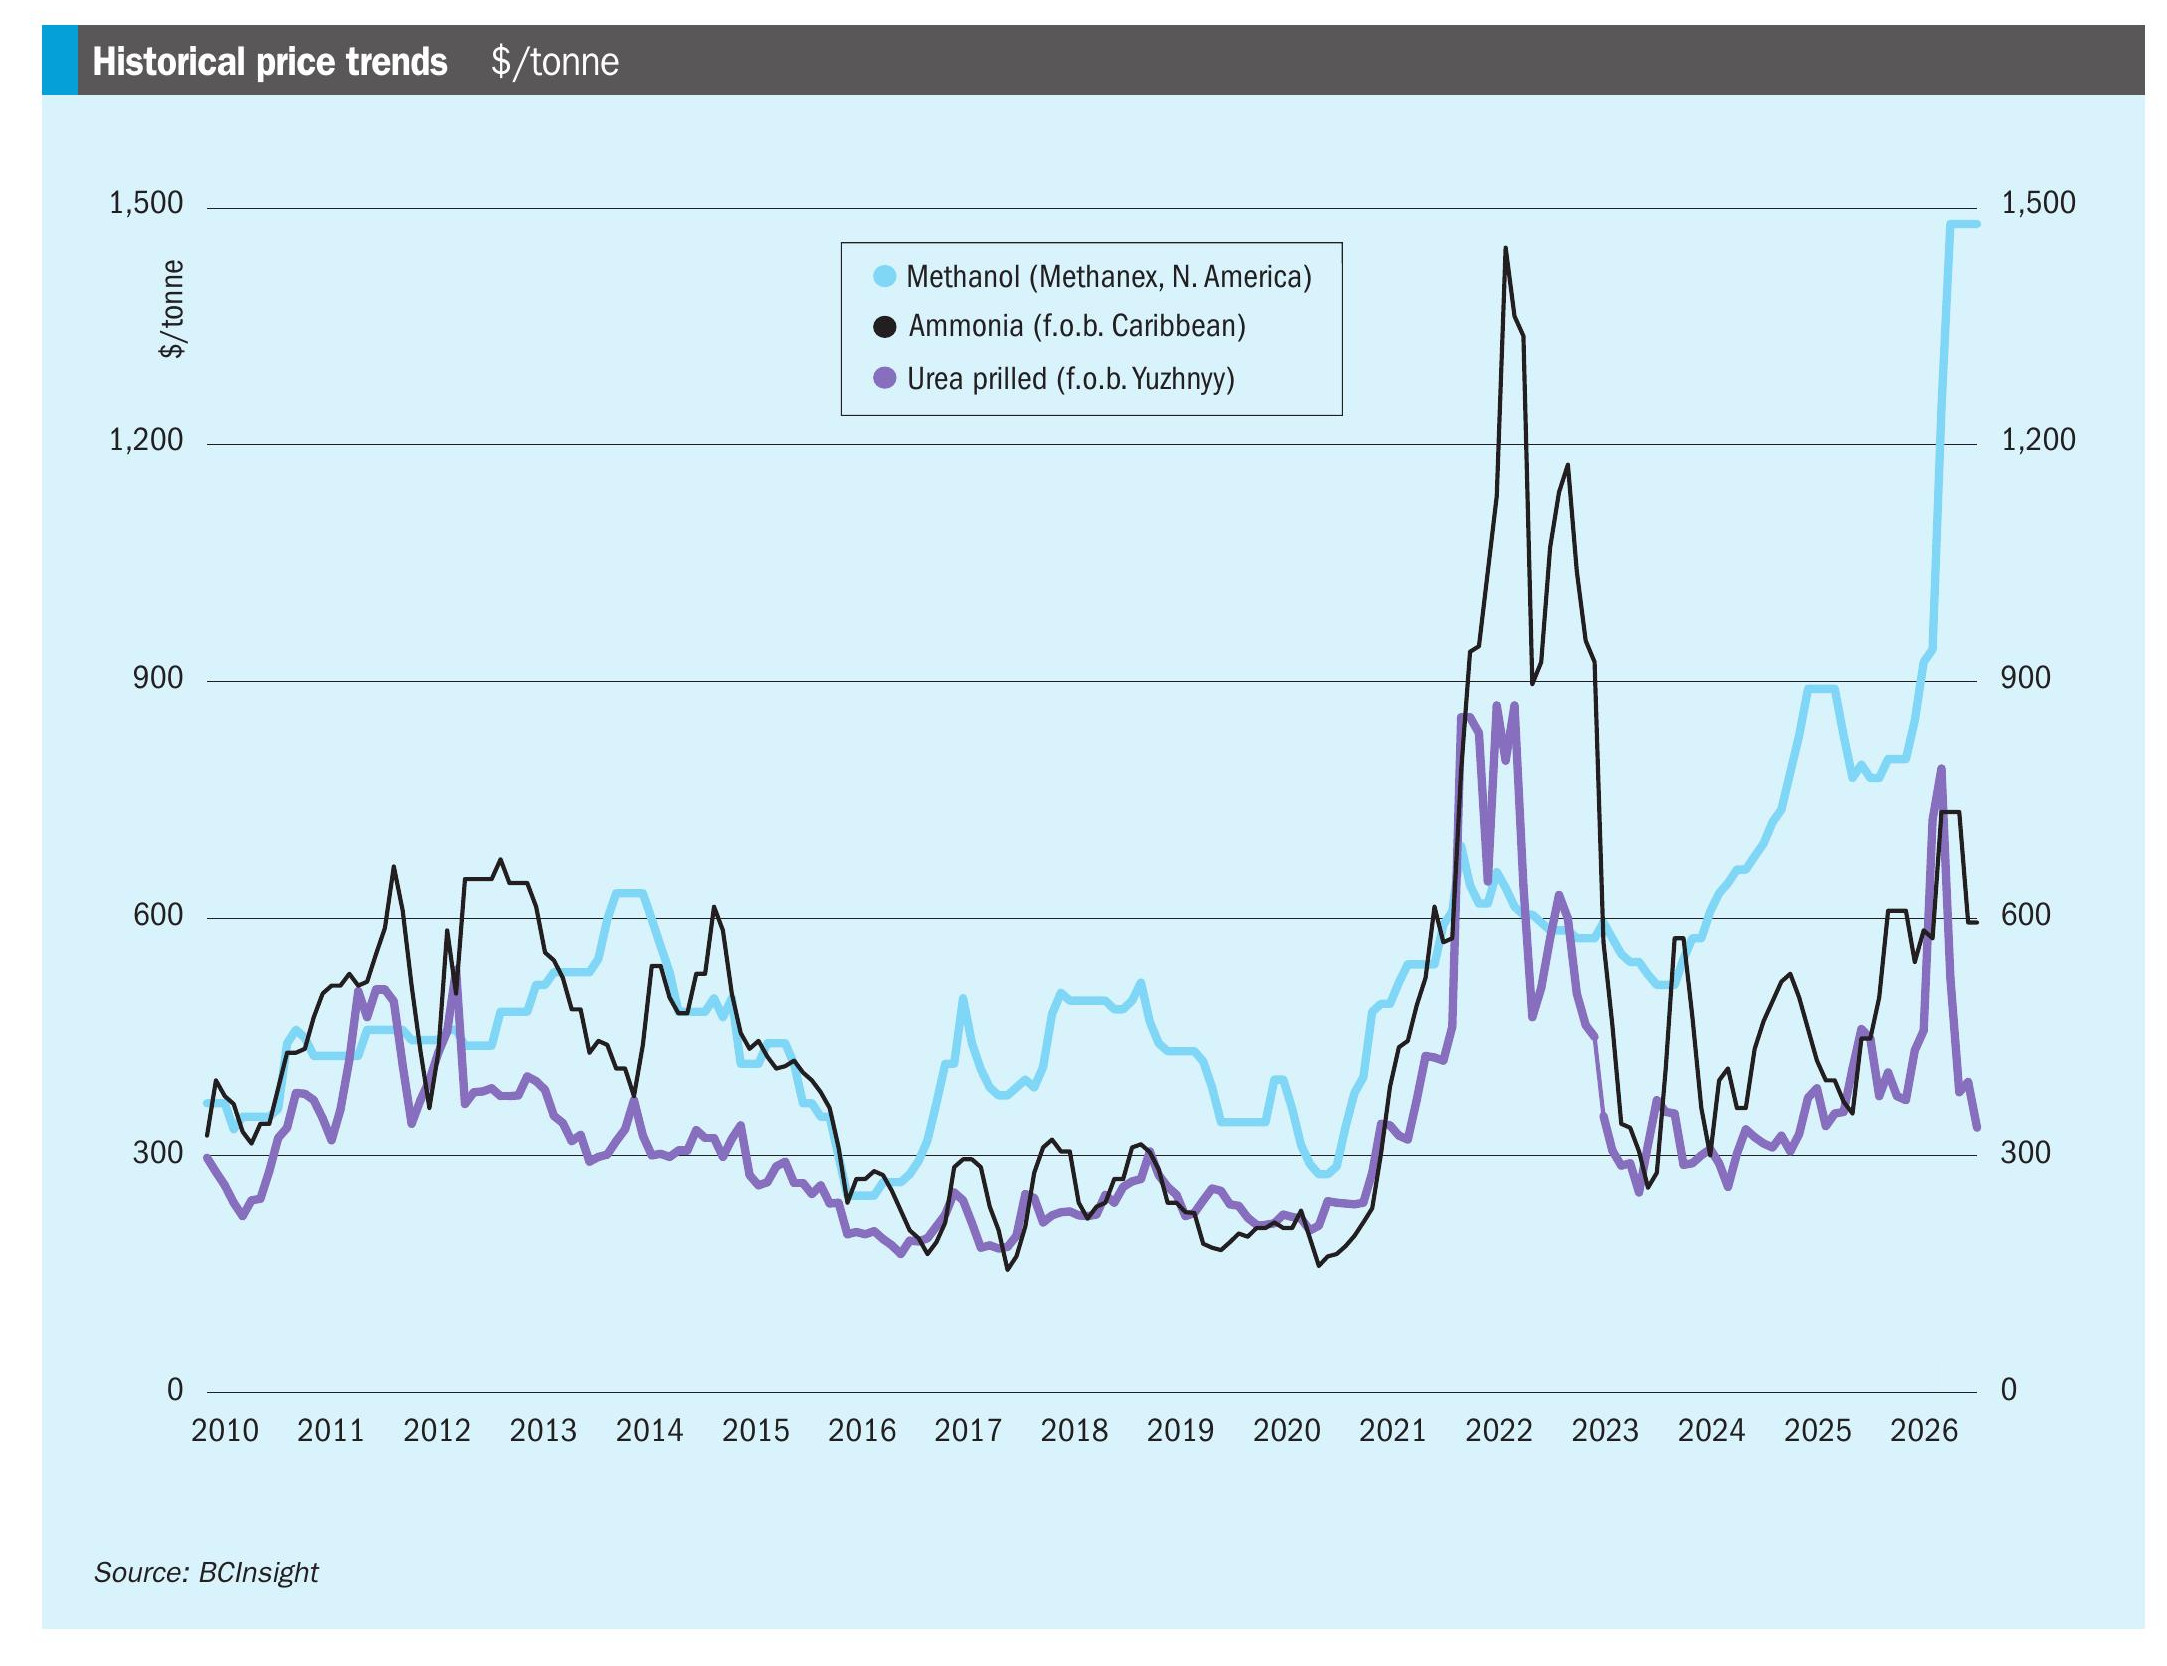
Historical price trends $/tonne
AMMONIA
- Prices in the Eastern Hemisphere, whilst still flat-to-firm, do not appear as supported as they have been over the past month, whilst indexes. There are still no signs of softening in the Far East although demand remains underwhelming and supply improving. While production in Indonesia is said to be back up and running, traders do not expect any spot cargo to emerge in July other than possibly some small part cargoes. August could see spot offers.
- India could see higher prices as there is still demand to be covered. The resolve of suppliers West of Suez should be tested next week in Europe and when the Tampa price should also be settled for July.
- West of Suez look balanced for the time being, with regional supply issues seemingly counteracted by a lack of demand.
UREA
- Urea prices have been firmer in June due to supply-side issues, in China, Egypt and to a lesser extent Indonesia. Demand for July tonnes should in theory keep prices firm, but the market has been nervous of committing too far forward.
- The next tender from India is expected to signal the direction that the market takes. In the absence of supply from China, which is facing government restrictions, prices are likely to move higher to cover an Indian tender.
- However, if Indian buyers hold off, buyers in Latin America and Europe could see lower numbers. This slide was already apparent in Brazilian prices towards the end of June.
- There is also speculation that India may buy more urea to compensate for an apparent shortage of DAP. RCF has twice tendered for 100,000 tonnes of DAP at the end of June and start of July.
METHANOL
- US methanol pricing remained robust, driven by increased demand from downstream derivative industries. The delayed start-up to Methanex’s Geismar 3 plant in Louisiana, due to refractory issues in the autothermal reformer, and its pushback to Q3 2024, has also curtailed expectations for abundant supply, particularly affecting exports to major markets like South Korea and China. Other shutdowns, including gas supply curtailments in Trinidad, have also contributed to a tight market in the Americas.
- In Asia, Methanex methanol, increased its Asian contract price (ACP) for June 2024 by $20 month-on-month to $420 per ton, the highest since March 2023.
- Egypt was also affected by gas supply curtailments, with Methanex idling its 630,000 t/a plant. However, lacklustre demand in Europe has kept prices relatively flat there.