Nitrogen+Syngas 386 Nov-Dec 2023

30 November 2023
Price Trends
Market Insight courtesy of Argus Media
NITROGEN
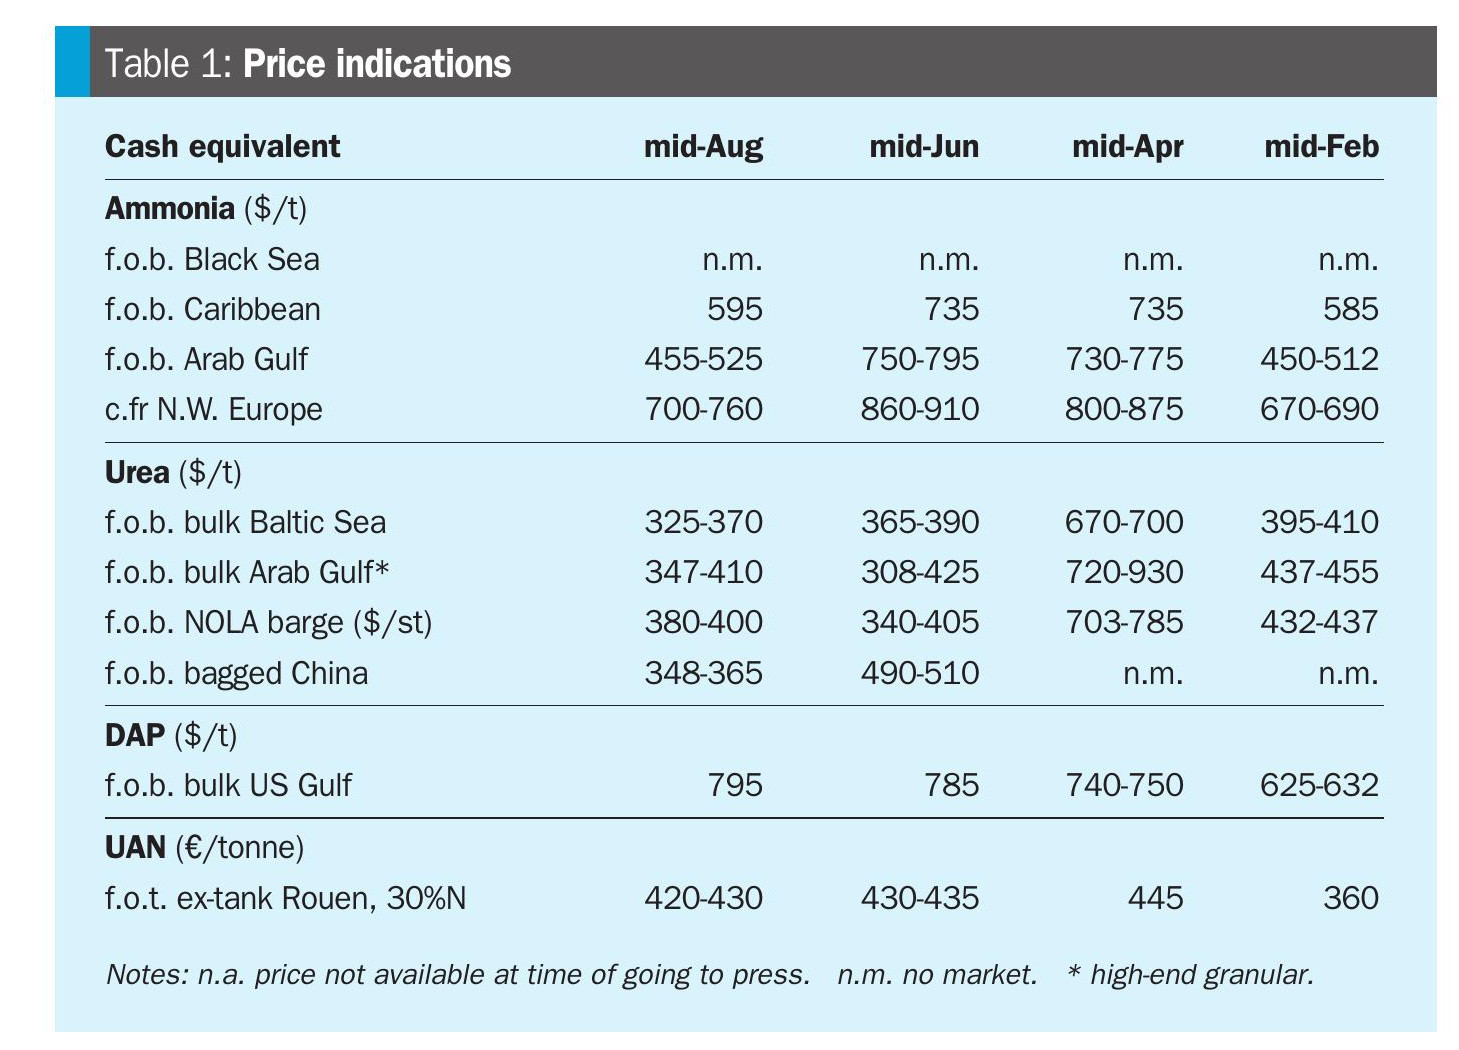
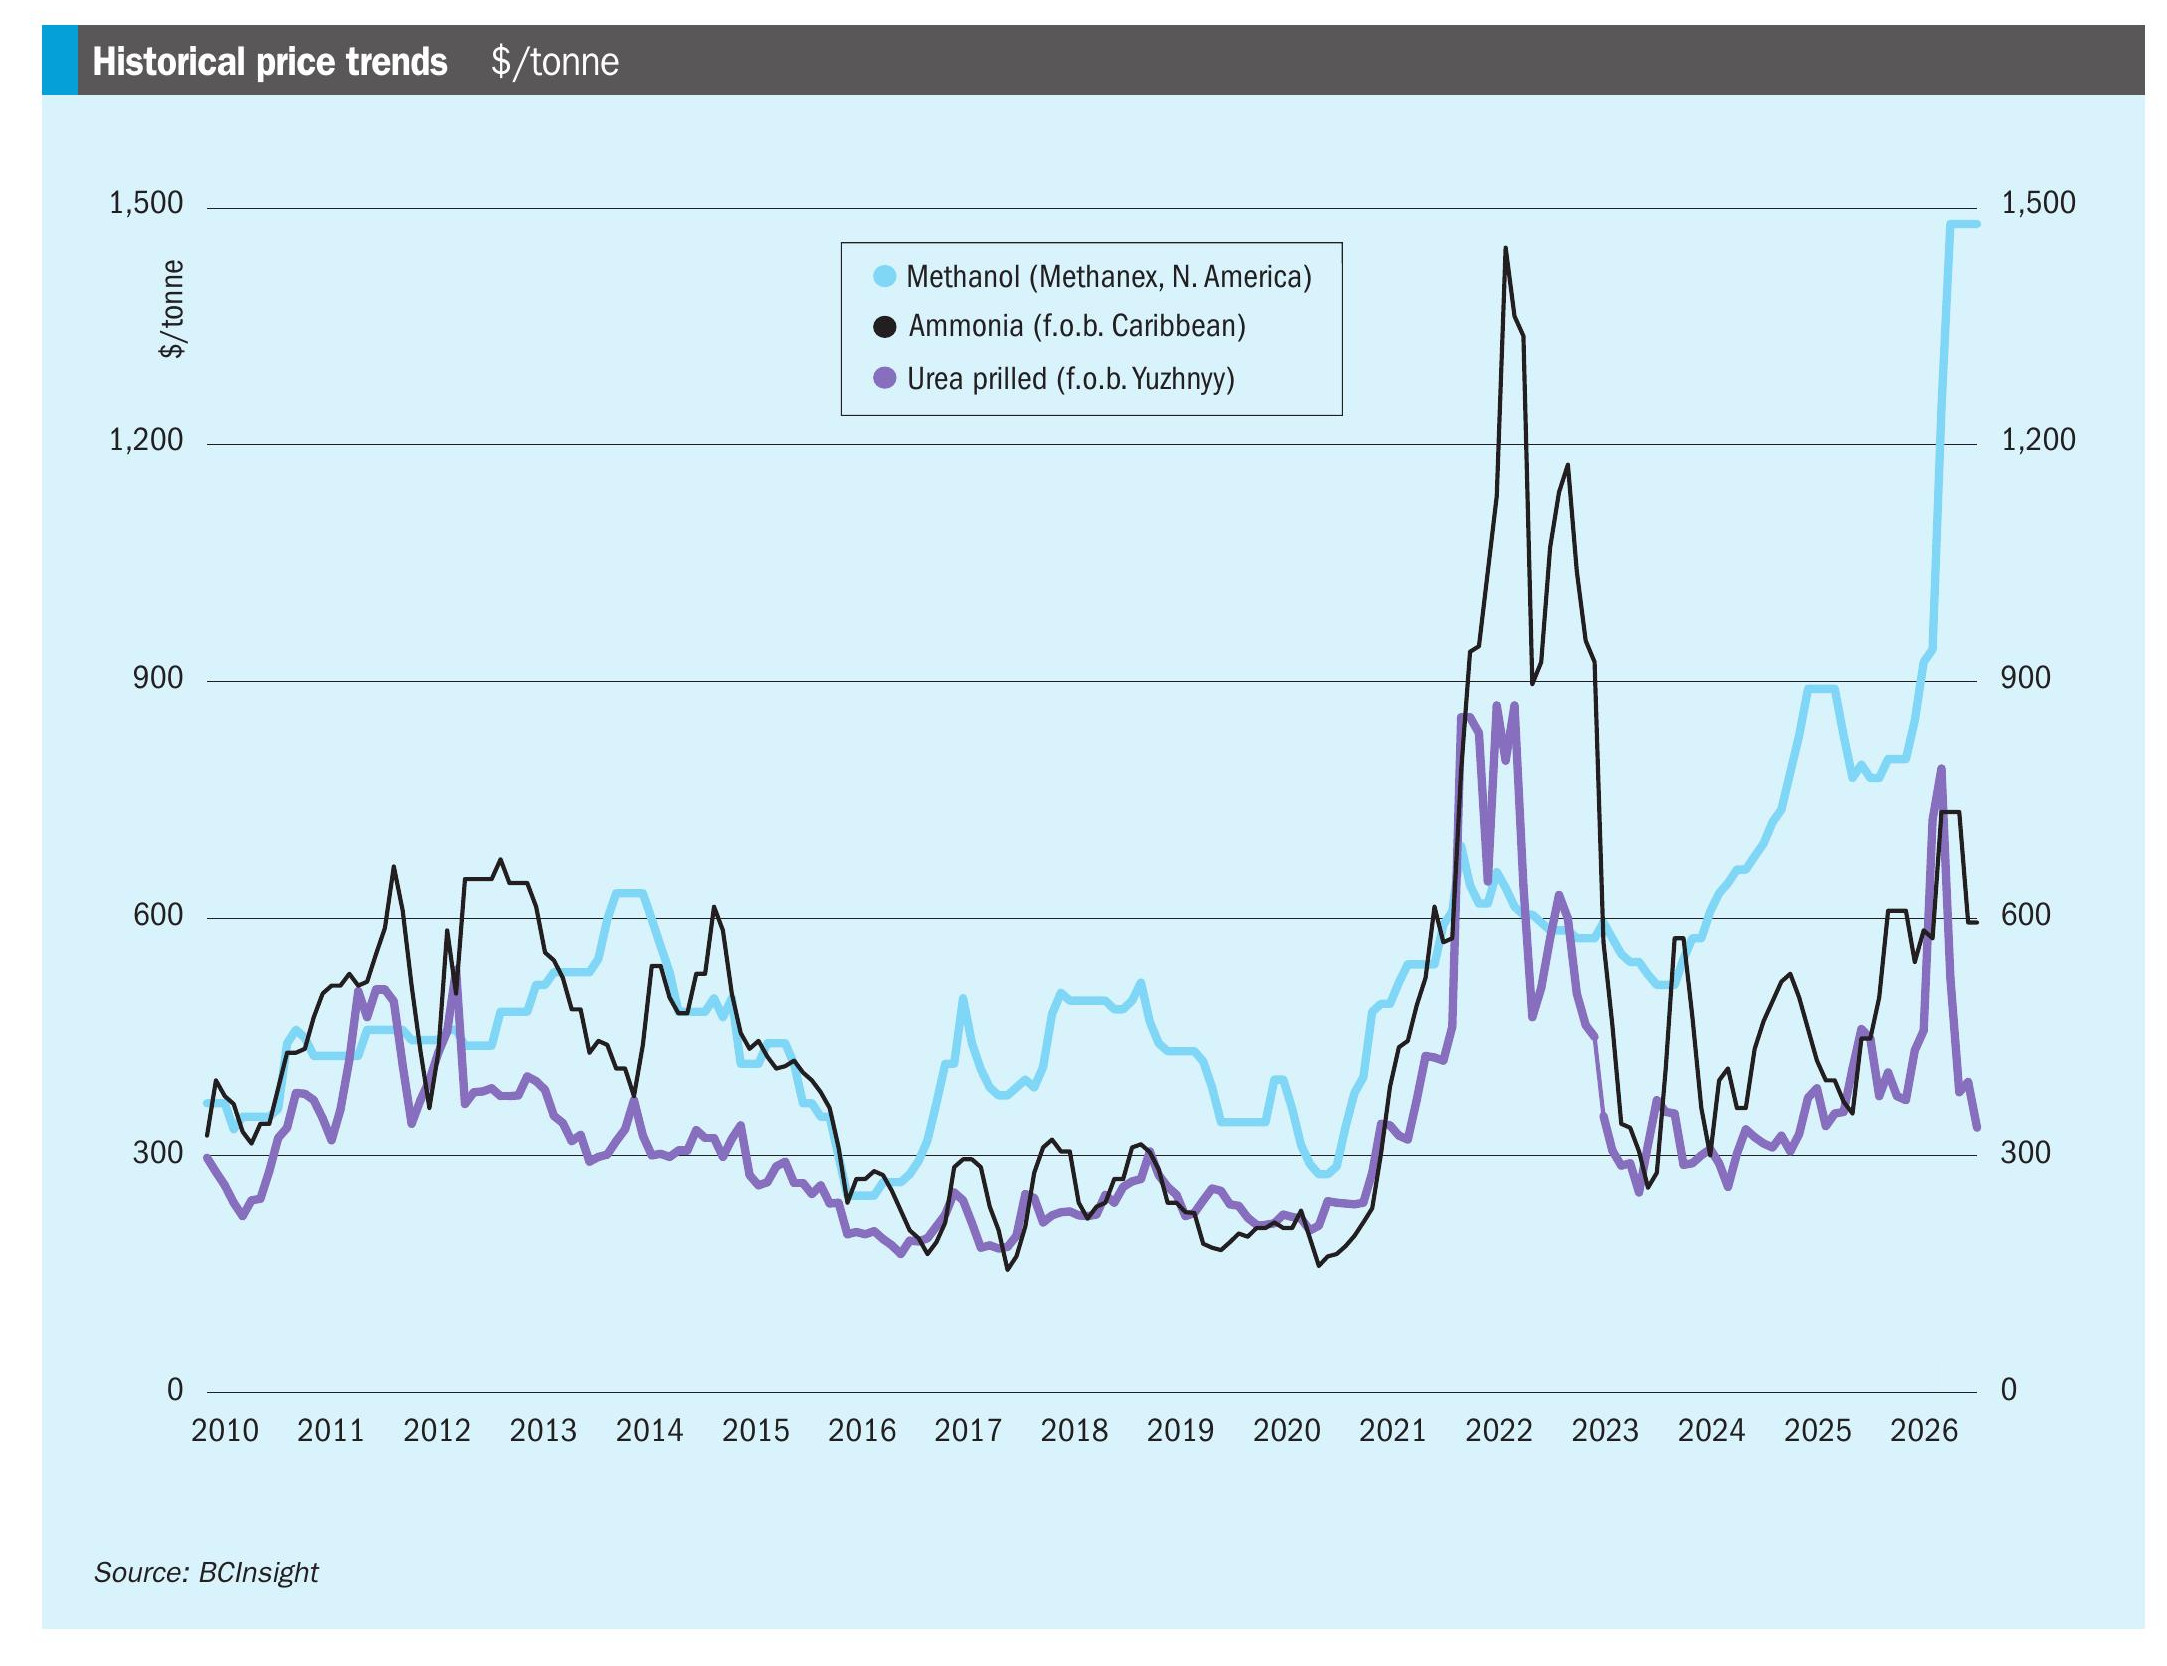
A $50/t rise to the Tampa ammonia contract for November has kept the near-term outlook relatively stable, and price ranges are narrowing across most regions with sellers unable to achieve prices above last done business. The Tampa settlement brought the region more in line with European delivered prices, but a lack of demand is underpinning most import regions, and weighing on price negotiations for spot cargoes.
Industrial demand for ammonia remains below average in Asia, Europe and the Americas, but this is being cancelled out by additional seasonal demand from the fertilizer sector. Supply is steadily improving in key supply regions, apart from Algeria, keeping buyers out of the market, anticipating lower prices in December.
Recent market drivers include Tampa price rises: Yara and Mosaic’s Tampa monthly contract price was announced at a $50/t increase for November, settling at $625/t c.fr. This nets back to $575-580/t f.o.b. Caribbean. Meanwhile Pupuk Indonesia is looking to issue a sales tender at the end of October/start of November. The spread between European production costs and import prices remains relatively narrow, but no fresh curtailments in Northwest European ammonia production have been confirmed yet in the region.
China domestic ammonia prices have risen. Further exports are unlikely in the near term, as a surge in Chinese domestic ammonia prices limits fresh offers, and supply improves in southeast Asia. The December outlook is pointing towards lower prices as seasonal fertilizer demand wanes and buyers wind down stocks ahead of the end of the year.

Urea prices fell again in most regions in late October as limited import demand – except from India – weighed on the global balance. India secured 1.7 million tonnes of urea under IPL’s 20 October tender at $400-404/t c.fr, with low demand in other regions and high producer inventories driving some suppliers to accept lower netbacks than they had previously hoped for.
Prices in the other major import markets generally fell. Brazil mostly traded in small lots and oscillated between $390405/t c.fr, while US prices slipped and Europe was almost silent.
Recent market drivers include Chinese export controls; ambiguity in the intensity of the restrictions on urea exports from China, particularly those to India, and this continues to cause uncertainty in the market.
Barring any shocks from outside the market, cautious importer buying patterns seem set to continue, which should limit the extent and duration of any price rally. But strong sales commitments to India and impending rise in European and Brazilian demand should limit the downside risk to prices.
END OF MONTH SPOT PRICES
natural gas

ammonia

urea

diammonium phosphate